Drug Channels delivers timely analysis and provocative opinions on pharmaceutical economics and the drug distribution system. Drug Channels reaches an engaged, loyal and growing audience of more than 100,000 subscribers and followers. Learn more...
Employers pharmacy benefit design changes determine who pays for a prescription and who gets the savings. Lower net plan liability on a prescription can reflect a lower drug price, a larger patient contribution, or more manufacturer funding. Those outcomes have different impacts on the patient.
Our latest review shows how differently employers structure those payments: 71% of covered workers in non-health savings account (HSA)-qualified plans have four or more prescription drug benefit tiers, compared with 41% in HSA-qualified plans.
But the simpler-looking benefit can expose patients to more percentage-based cost sharing. Among workers in plans with at least three tiers, 52% of those in HSA-qualified plans face coinsurance for preferred drugs, compared with 15% in non-HSA plans.
The consequential difference is the impact on the patient. Coinsurance can expose patients to a drug’s price before manufacturer rebates, even when those rebates substantially reduce the employer’s net cost. Fewer benefit tiers provide little assurance that those savings are shared with the patient at the pharmacy.
Below, we examine the latest data on employer-sponsored pharmacy benefits and show how tier structures, cost sharing formulas, rebates, and manufacturer assistance divide costs between plans and patients.
Want to hear more about what's coming next year?
Join the upcoming live video webinar Drug Channels Outlook 2027 on December 11, 2026, from 12:00 p.m. to 1:30 p.m. ET. More details here. There are special discounts if you want to bring your whole team!
Today's guest post comes from Geoff Chaiken, CEO at BlinkRx.
Geoff examines the different roles of telemedicine, consumer rebates through cash discount cards, and cash-pay pharmacies in direct-to-patient (DTP) prescription access. He argues that while each can improve access, none fully addresses the challenges of prescription fulfillment and adherence. He makes the case for a more comprehensive approach that integrates affordability, insurance coverage, and pharmacy fulfillment throughout the patient journey.
To learn more about BlinkRx's RxOS prescription operating system, visit BlinkRx.
This split is a belated acknowledgement that the synergies between CVS Pharmacy and Caremark were overblown from the start. As I argue below, CVS Pharmacy will have greater freedom to make the hard choices—and also find new friends. Regulatory and legislative risks are real, but I view this primarily as a strategic and financial decision.
I’ll have a lot more to say about the future of vertical integration during the Drug Channels Outlook 2027, which will be my final DCI webinar.
Don’t miss this final opportunity to hear Adam’s unfiltered, data-driven outlook on the forces shaping the drug channel—and what they mean for your organization in 2027 and beyond.
For more than 20 years, Adam has brought you an unfiltered, data-driven look at the most important trends, market forces, and policy developments in the drug channel. In his final webinar before retiring from DCI, he’ll examine where the industry is heading—and what his two decades of tracking its evolution reveal about what comes next. Adam will share his unfiltered outlook on key issues where he has been a pioneering voice, including:
Consolidation, vertical integration, and industry power
The 340B Drug Pricing Program and the 340Boom
Accumulators, maximizers, and shady alternative funding programs
The Gross-to-Net Bubble and SpongeBob SquarePants
The Net Pricing Drug Channel (#NPDC)
Antonio, Tyler, and Bryce will also explore:
PBM reform: Real change or more of the same?
What new CMS and DOL rules mean for plan sponsors and the PBM business
The Inflation Reduction Act’s impact on Medicare Part B and Part D
The future of pharmacy profits and reimbursement
Patient-paid prescriptions and direct-to-patient disruption
The November elections’ impact on the drug channel
What’s ahead for most favored nation pricing
Biosimilars and the buy-and-bill market
Wholesalers’ next growth opportunities
As always, the speakers will clearly distinguish their opinions and interpretations from the objective facts and data.
This 90-minute video webinar will include a dedicated Q&A session, during which attendees can unmute and engage directly with Adam and the other speakers.
Can’t attend the live event? After each event, every registrant will receive an email with information on how to view a replay of the video recording. Every registrant will also be able to download a PDF of the full slide deck.
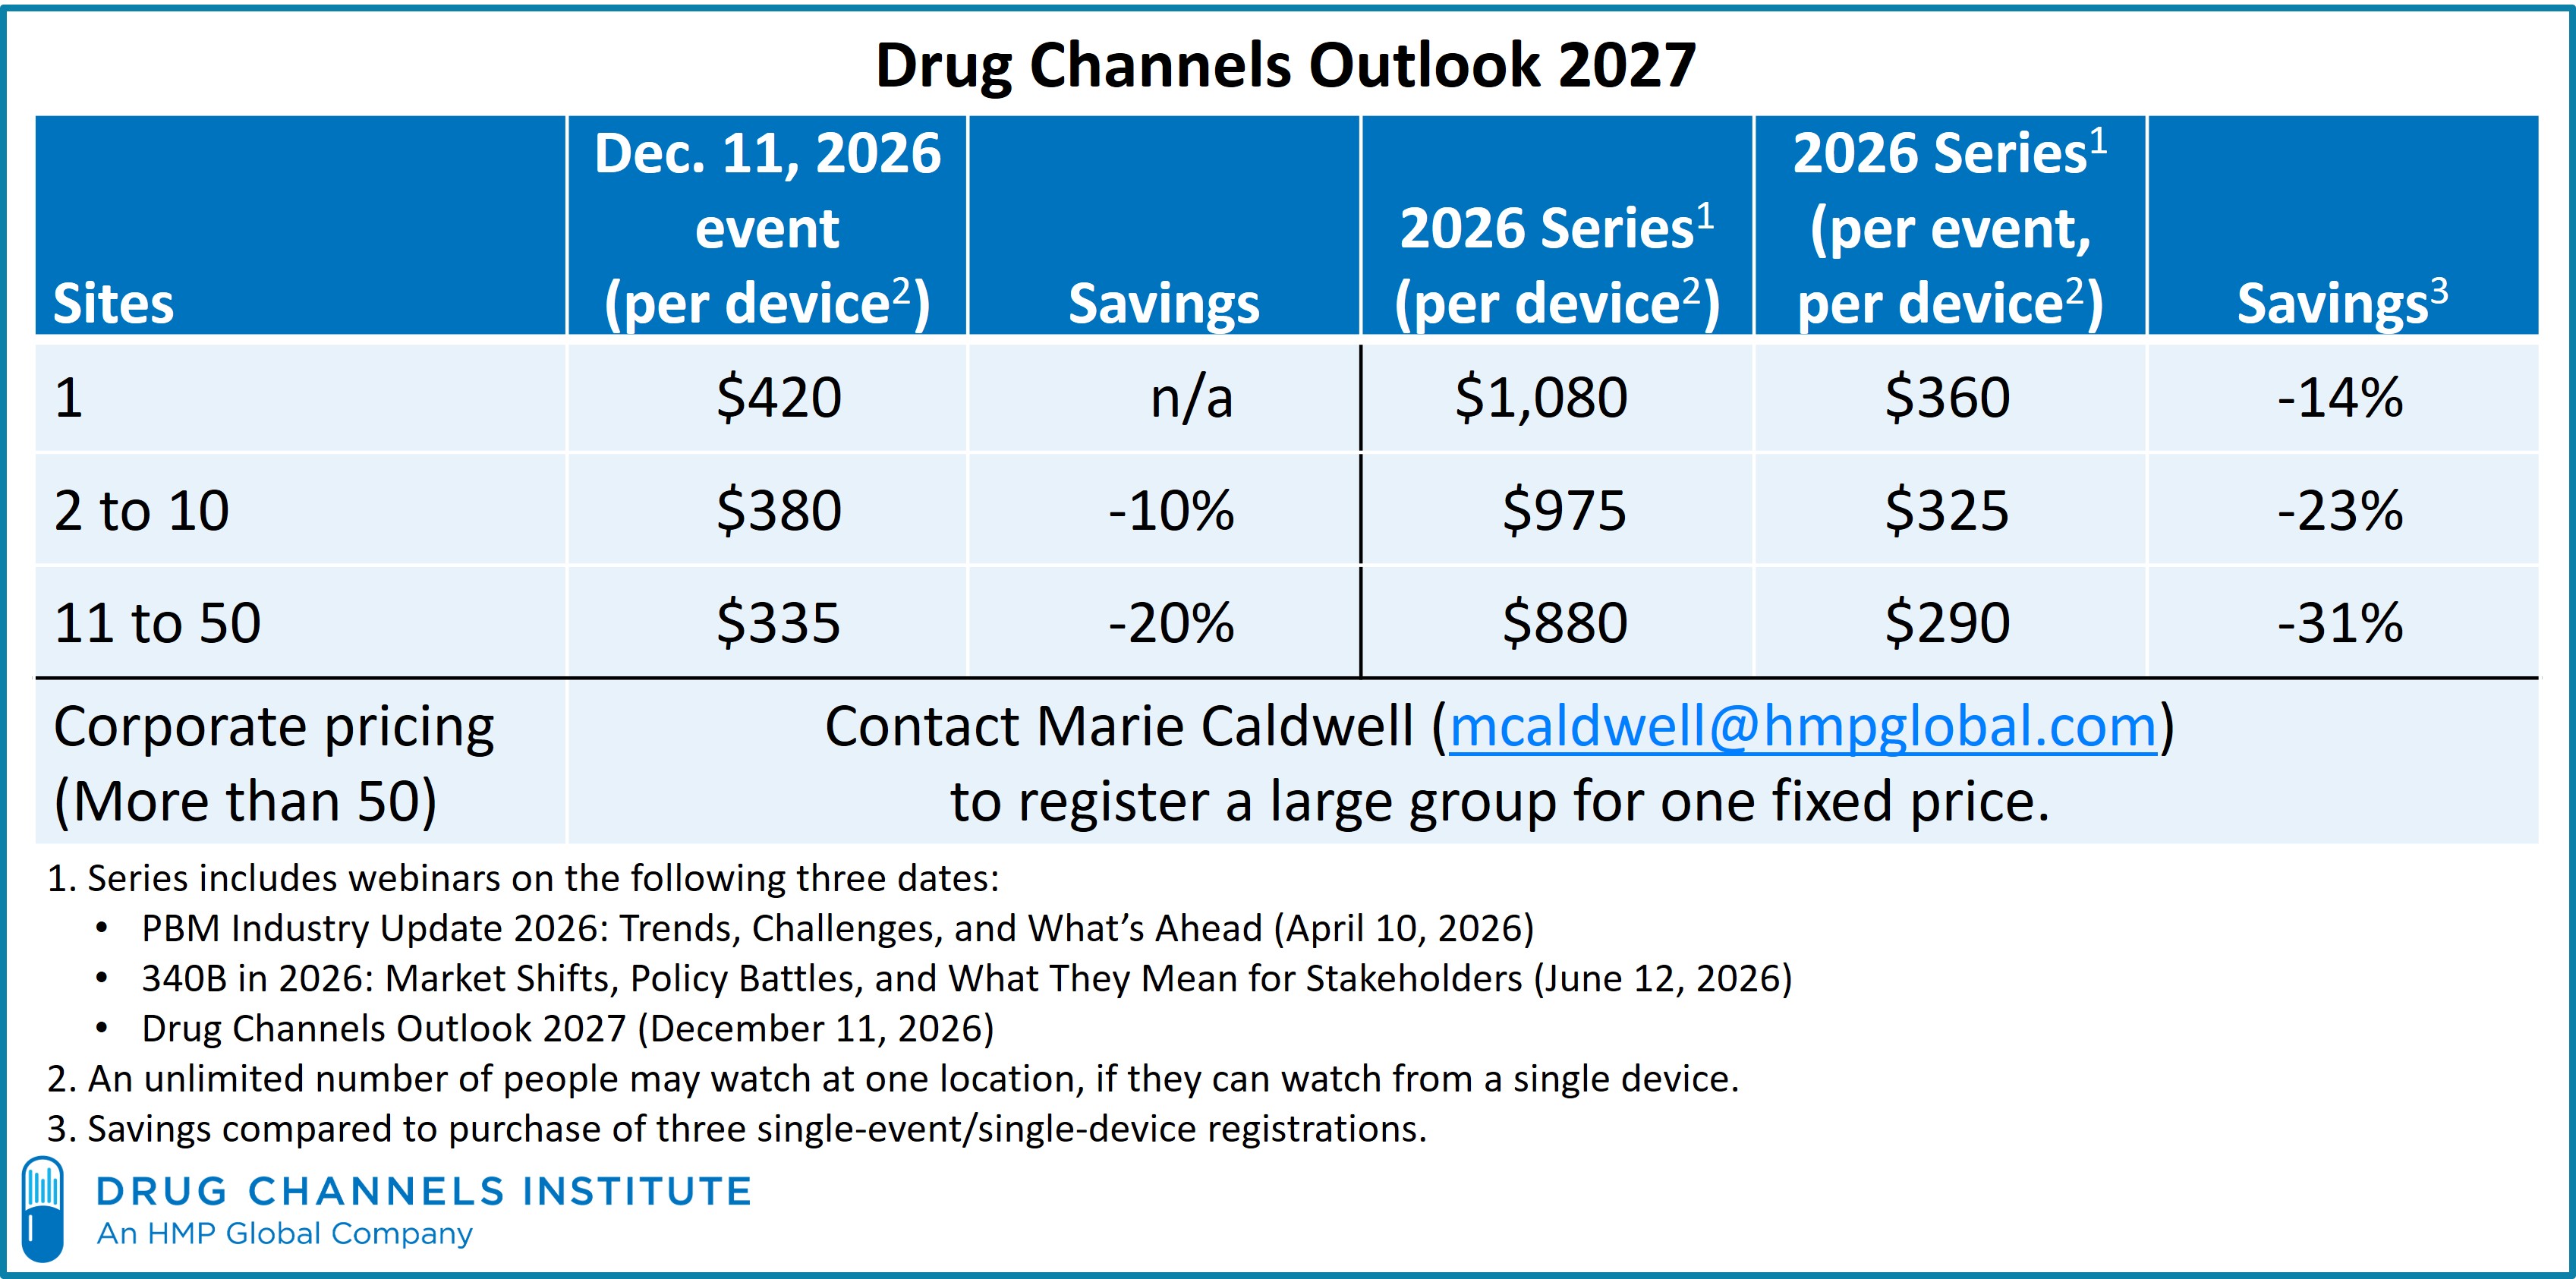
Register for $420 per viewing device. Within one business day of registering, you'll receive a unique Zoom access link and details for adding the event to your calendar.
Special Team Discounts
We offer substantial savings when an organization purchases multiple registrations. An unlimited number of attendees can watch together at a single physical location using one registered device.
Important Reminder: Each viewing device must have its own registration. Attendees may not record the webinar or broadcast its audio or video to other devices or locations.
Register now. All discounts will be automatically calculated based on the number of registrations you enter in your cart.
Purchasing access for multiple devices or locations? We’ll contact you for your participant list. Alternatively, download this spreadsheet and email your registrants’ information to dcisupport@hmpglobal.com.
Watch and listen using any modern browser on a computer, tablet, or mobile device. (No telephone access.)
Each registrant will receive an email with a link to watch the event. This link is unique to the registrant and is valid for one registered viewing device.
Every registrant will also receive a link to download the complete slide deck.
This event is part of The Drug Channels 2026 Video Webinar Series. If you already purchased access to the series, you should already have received an email from Zoom with a link to access the December 11, 2026, event.
Organizations that purchased corporate access to The Drug Channels 2026 Video Webinar Series will receive a custom, branded signup link so employees can easily register. We will automatically refund payments from anyone at a company with corporate access who purchases a single registration using their corporate email address.
Each registration for a DCI webinar is valid for a single device at a single physical location. Attendees are not permitted to record, stream, share, or project a DCI webinar to other sites or locations. Purchasers who violate this limitation by recording, streaming, sharing, or projecting a DCI webinar to other sites, devices, or locations will be liable for the full cost of all locations that viewed the webinar. DCI reserves the right to prohibit purchasers who violate our terms from attending future DCI webinars.
Except for the corporate-access refunds described above, we are unable to offer refunds.
Today's guest post comes from Danny Sigurdson, Founder and CEO at Courier Health.
Danny examines how biopharma companies are approaching patient services, partner changes, and artificial intelligence in 2027. He argues that connected data and purpose-built technology can improve operational efficiency, accelerate access to therapy, and enhance the patient experience.
Today's guest post comes from Anurati Mathur, Co-Founder & CEO at Sempre Health.
Drawing on conversations with pharmaceutical market access leaders, Anurati examines whether traditional copay assistance programs are delivering sufficient value. She argues that automatic point-of-sale discounts often subsidize prescriptions that patients would have filled anyway. She makes the case for a more targeted, data-driven approach that aligns affordability spending with patient behavior to improve adherence and gross-to-net (GTN) performance.
Today's guest post comes from Gerard Rivera, Co-Founder & CEO at RIS Rx.
Gerard Rivera examines how copay programs and real-time gross-to-net (GTN) revenue protection can work together to support patient access and program performance. He highlights how simpler program design, timely data, and responsive action can help manufacturers manage affordability programs while preserving patient experience.
PBMs outside the Big Three still earn higher customer satisfaction ratings, but their lead has nearly disappeared.
Meanwhile, plan sponsors are inviting alternatives into their RFPs, and some are changing vendors. Research on 2027 benefits planning suggests the shopping will continue.
That combination points to a new test for alternative PBMs—one where they have to turn their pitch into value that plan sponsors continue to see after they sign a contract.
Below we examine the shrinking satisfaction advantage, the choices plan sponsors are considering for 2027, and why the grass may not always be greener on the alternative PBM side.
The Drug Channels Leadership Forum agenda is now available! Explore the agenda and request your invitation to this invite-only gathering of senior leaders from across the drug channel ecosystem. You must request an invitation to be considered for attendance.
December 8-10, 2026, W Philadelphia Exclusive Offer—Use promo 26DC10 to save 10%*
NAVIGATE THE CONVERGENCE: PREPARE, DON'T PREDICT
In the next eighteen months, every assumption of pharmaceutical channel strategy breaks all at once. The patent cliff, WAC reductions, loss of exclusivity, medical benefit shifts and cash and self-pay emergence have left trade and channel professionals in need of complete strategy rebuilds.
The pharmaceutical channel is being rewritten in real-time. Leaders who attend will gain the insights needed to navigate these changes while competitors are left playing catch-up. In these times, falling behind means losing your competitive edge.
What can you expect?
The event features a stellar lineup of industry leaders, including Bill Roth of IntegriChain, who will deliver the keynote address, The Convergence—When Pharma’s Channel Assumptions All Break at Once. Other notable speakers include:
Rena Goins, Executive Director, Global Trade, Regeneron
Susan Farkas, Executive Director, US Payers & Specialty Pharmacy, AstraZeneca
Mike Petit, Director, U.S. Channel Accounts, Intercept Pharmaceuticals
Martine Avello, Director, Channel and Distribution, BioMarin Pharmaceutical Inc
Thomas Scalone, Director, Trade Strategy and Operations, Bristol Myers Squibb
Program highlights:
A Look From Wall Street: Dealmaker insights on M&A and vertical integration trends over the next 12–24 months
Trade Partner Insights: Direct feedback from trade partners on supply chain friction and operational challenges impacting the industry
Leveraging Technology: Discover how AI, digital tools and analytics are transforming trade strategies, specifically in pricing optimization, payer engagement and channel management
Tracks, Trainings and More: Focused content on supply chain, pharmacy models and health systems and pharma partnering, as well as a negotiation training and Women in Trade networking session
What attendees are saying:
“Most valuable conference of the year to understand pharmacy and distribution related topics. There is no second.”
“One of the best conferences I have ever attended. The speaker selection and topic covered from a strategic and tactical approach were extremely relevant to our business.”
Exclusive Offer – Download the agenda and register today–Use your exclusive promo 26DC10 to save 10%*
*Cannot be combined with other offers, promotions or applied to existing registration. Other restrictions may apply.
The content of Sponsored Posts does not necessarily reflect the views of HMP Omnimedia, LLC, Drug Channels Institute, its parent company, or any of its employees. To find out how you can publish an event post on Drug Channels, please contact Marie Caldwell(mcaldwell@hmpglobal.com).
As regular readers of Drug Channels know, U.S. distribution and dispensing channels for prescription drugs are undergoing significant evolution and consolidation as the changing economics of pharmaceuticals challenge conventional business models.
During this period of volatility, the core business model of the Big Three public pharmaceutical distribution companies—Cardinal Health, Cencora, and McKesson—remains intact. Put simply: Buy low, sell high, collect early, and pay late.
But as I explain below, wholesalers continue to position themselves as essential intermediaries by expanding their role across the drug channel and strengthening their economic fundamentals.
Read on for 10 key pricing, pharmacy, provider, and manufacturer trends that are driving the U.S. drug wholesaling industry.
The U.S. prescription drug market continues to expand, even as the foundations of the drug channel are shifting. Legislative intervention, pricing realignment, vertical integration, and alternative payment models are accelerating a transition away from a rebate-driven system built on high list prices and toward a marketplace increasingly shaped by net prices.
DCI’s seventeenth annual report examines what these changes mean for the pharmaceutical wholesalers and specialty distributors at the center of the U.S. drug channel. With nine chapters, more than 430 pages, 193 exhibits, and more than 940 endnotes, this report is unmatched in scope and depth.
Order today to download the fully updated, revised, and expanded 2026-27 edition at special launch prices. Special launch prices will be available through October 26, 2026. Act now to maximize your savings.
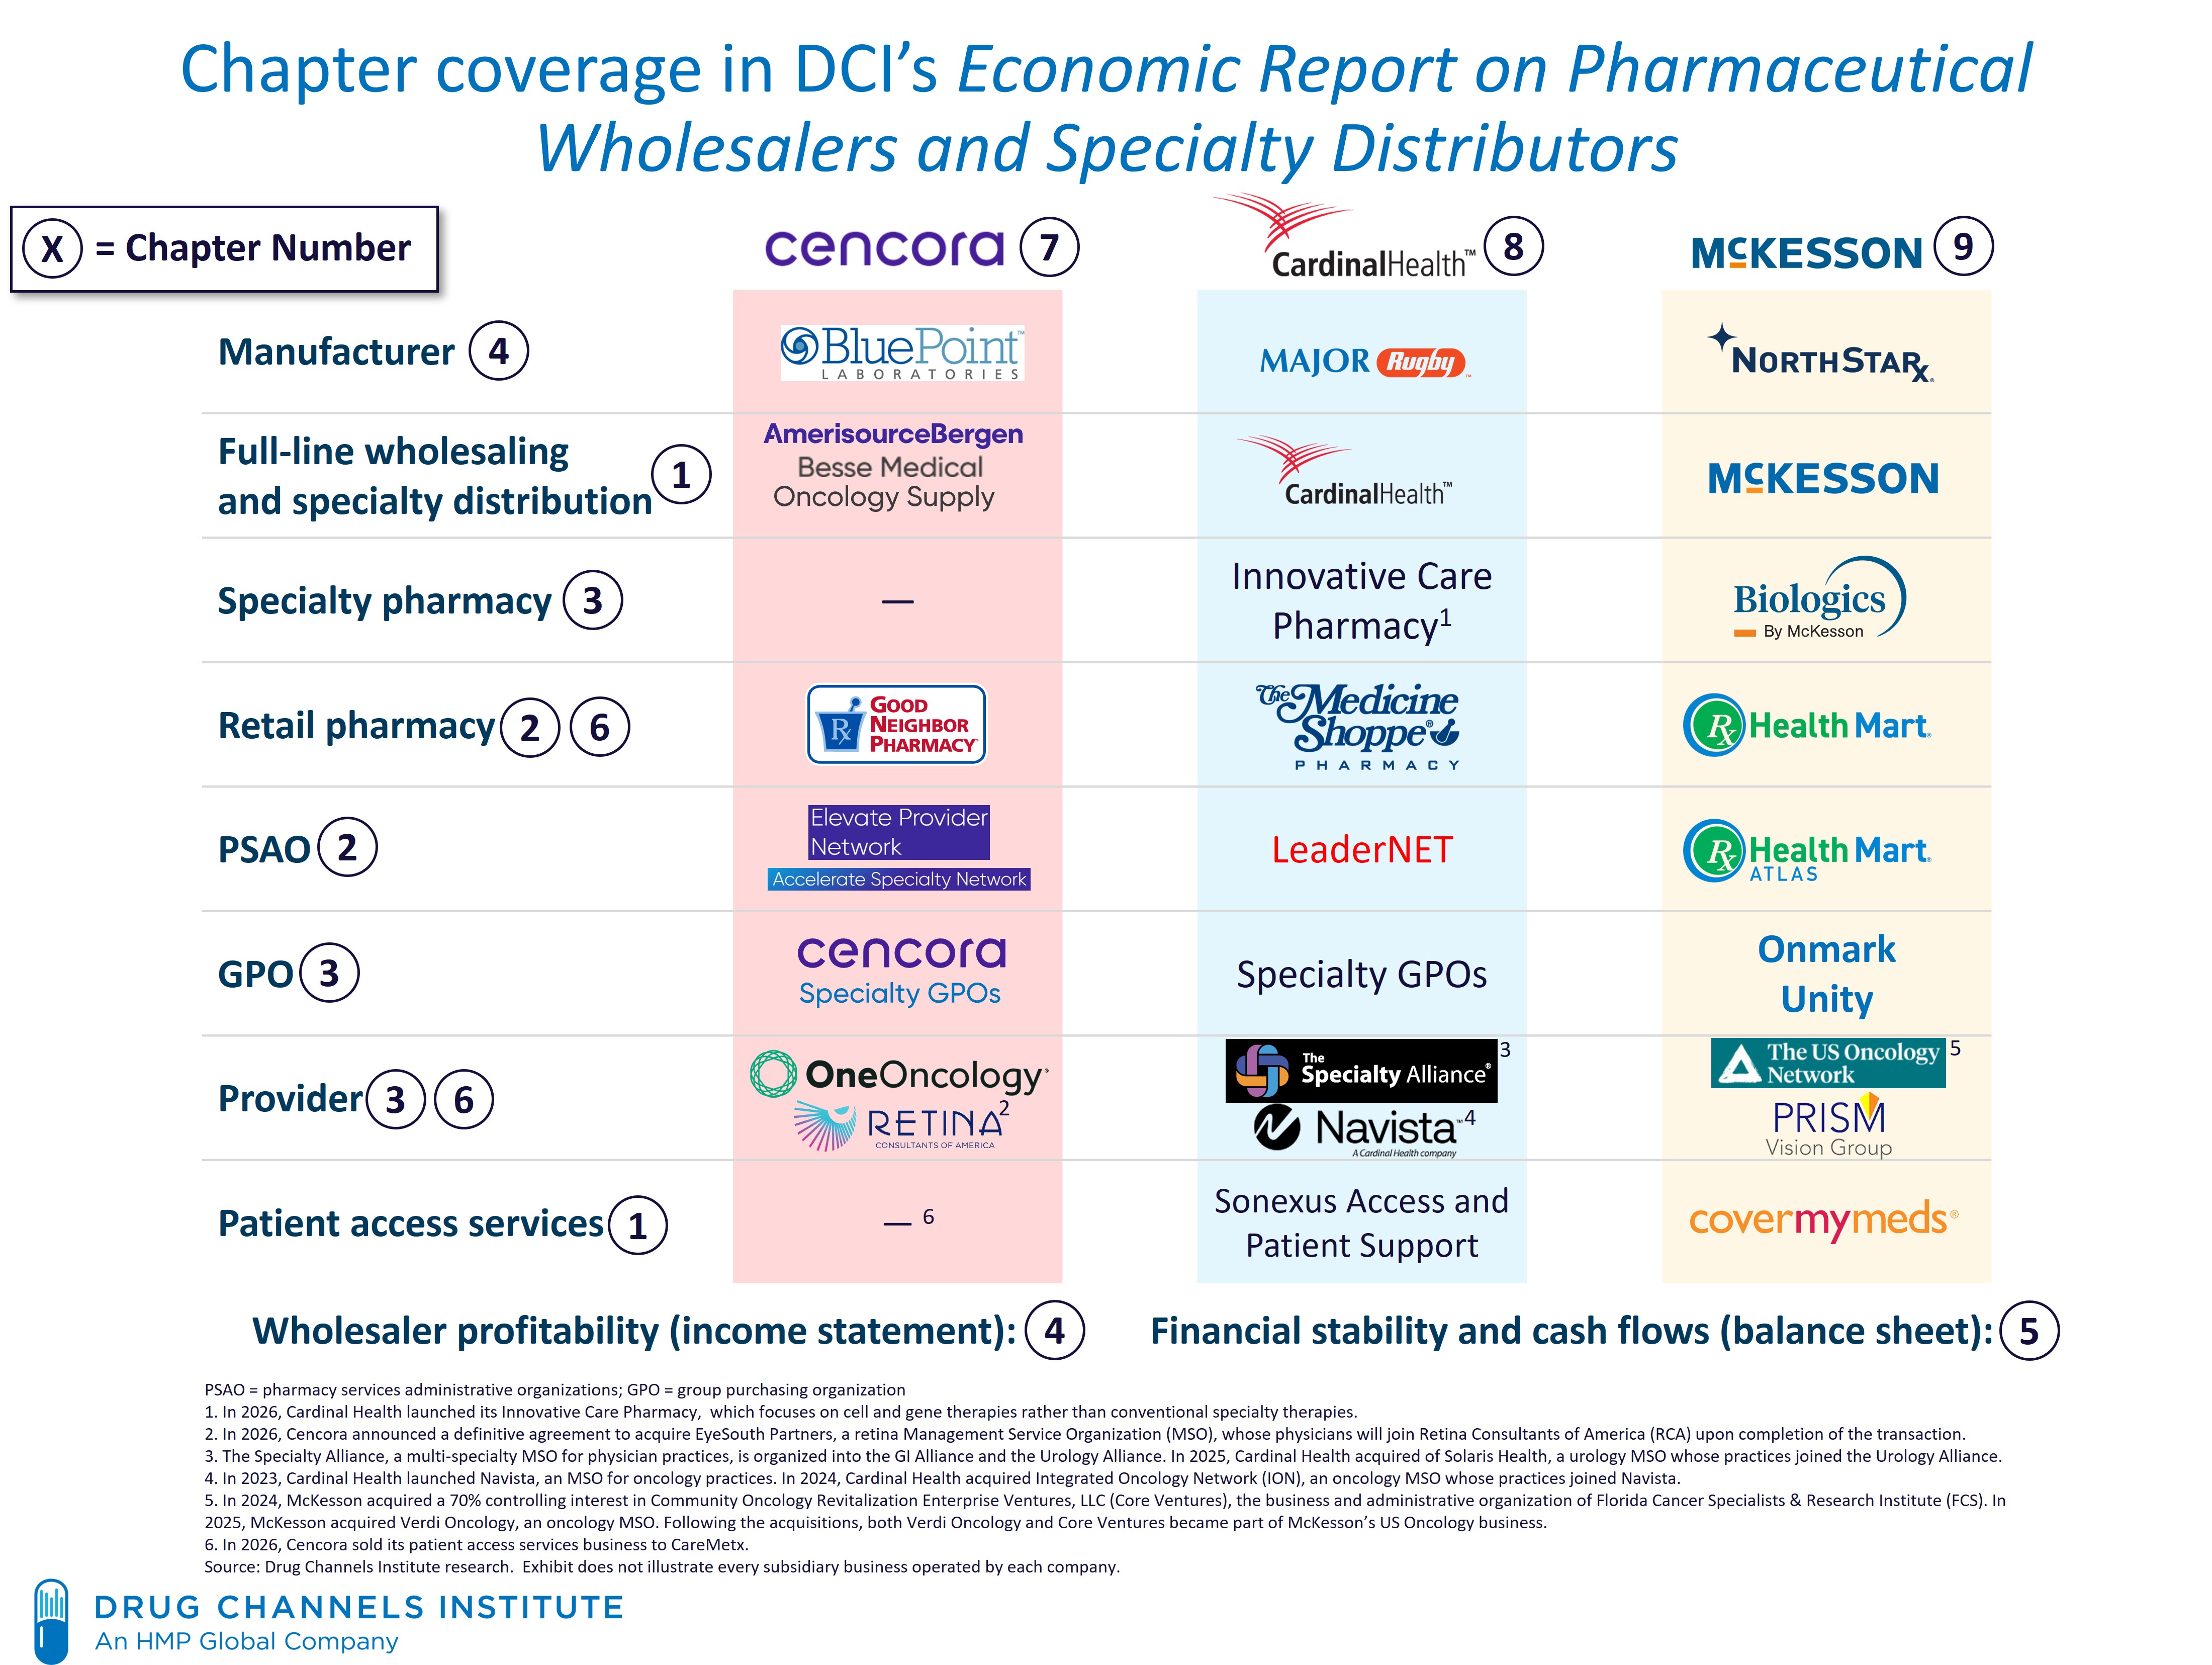
The chart below highlights the vertical alignment and diverse roles of Cencora, Cardinal Health, and McKesson within the U.S. healthcare system. The circled numbers identify the report chapters that explain and analyze each business.
[Click to enlarge]
The new edition provides the most current financial and industry data about pharmaceutical distribution. Among the major findings and expanded areas of coverage:
Drug distribution revenues for the Big Three public wholesalers are projected to reach $933 billion in 2026, although revenue growth has slowed from double-digit to mid-single-digit rates.
The largest wholesalers have invested more than $20 billion in physician management services organizations, transforming their roles in buy-and-bill markets.
Changes in drug pricing, direct-to-patient models, and other emerging channels are accelerating the industry’s transition toward a Net Pricing Drug Channel.
The report examines the evolving economics of biosimilars, cell and gene therapies, the 340B Drug Pricing Program, and implementation of the Inflation Reduction Act.
DCI’s proprietary economic models reveal differences in the business strategies, market positions, financial performance, and underlying profitability of Cencora, Cardinal Health, and McKesson.
There are 193 exhibits in the 2026-27 edition, compared with 187 in last year’s report. Most are new or fully updated.
Thank you for your continued interest in our research. Please email us (dcisupport@hmpglobal.com) with any questions before purchasing. We look forward to helping you succeed in the evolving U.S. drug channel.